What is the scope and industry significance of the Busbar Market?
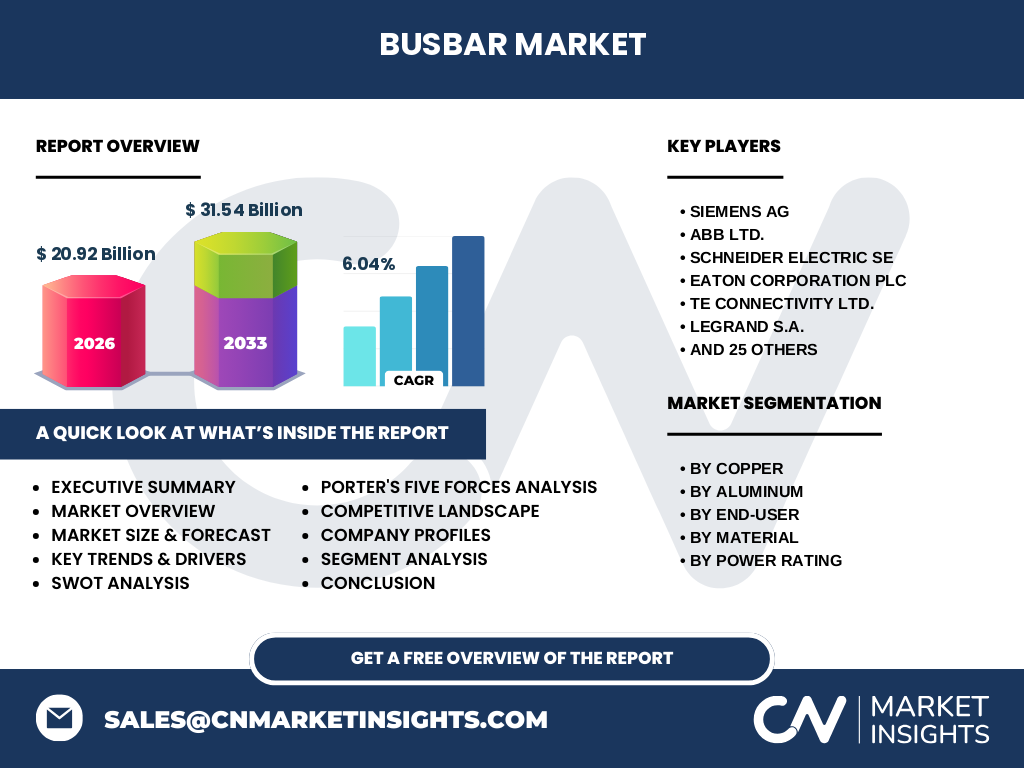
Our analysis indicates that the Busbar Market valuation stands at $20.92 Billion in 2026, serving as the foundational electrical backbone for heavy industrial distribution, renewable energy integration, and modern data center power architectures requiring high ampacity and thermal efficiency.
Key market drivers, restraints, challenges, and opportunities shaping Busbar Market
Rapid urbanization and grid modernization act as primary growth catalysts, while volatile copper and aluminum pricing presents continuous margin compression. Compliance with stringent IEC and IEEE standards creates technical entry barriers, though booming EV charging infrastructure unlocks lucrative expansion pathways for high-rating systems.
Emerging trends and growth patterns in Busbar Market
The industry is witnessing an accelerated shift toward compact sandwich-type distribution systems and eco-friendly insulating materials. Leading innovators like Schneider Electric SE and ABB Ltd. are pioneering smart monitoring busbars embedded with IoT sensors to predict thermal overloads in mission-critical facilities.
How did the COVID-19 pandemic affect Busbar Market and the recovery trajectory?
Pandemic-induced supply chain fractures and prolonged semiconductor shortages temporarily paralyzed switchgear manufacturing in 2020. However, post-crisis stimulus packages targeting green energy transitions fueled a sharp V-shaped recovery, pushing production back to pre-pandemic highs through localized sourcing and automated fabrication.
Competitive benchmarking and strategic dynamics in the Busbar Market
The competitive landscape is moderately consolidated, featuring tier-one electrical giants alongside specialized component makers. Market leaders leverage extensive global distribution networks and proprietary thermal management patents to defend market share against aggressive regional challengers.
Executive summary of key findings about the Busbar Market
Proprietary research confirms strong, sustained expansion for the sector, driven by global electrification imperatives. The market is projected to surge from $20.92 Billion in 2026 to reach $31.54 Billion by 2033, expanding at a robust 6.04% CAGR.
Market forecast and projected growth from 2027 to 2033
Based on our econometric modeling, the Busbar Market will maintain an upward trajectory, scaling from its 2026 baseline to achieve $31.54 Billion by 2033. This steady expansion, underpinned by a 6.04% CAGR, reflects sustained capital expenditure in utility grids and industrial automation.
Segmentation analysis by material, type, end-user, and power rating
The market bifurcates into Copper (including Electrolytic, Tinned, and Enameled Copper Busbars) and Aluminum (comprising Extruded, Rolled, and Welded Aluminum Busbars). End-user deployment spans Utilities, Industrial, Residential, and Commercial sectors across Low, Medium, and High power ratings.
Regional market analysis and geographic distribution
Geographic performance is heavily influenced by regional infrastructure spending and industrialization rates. Asia-Pacific dominates consumption due to massive grid expansions, while North America and Europe focus on replacing aging electrical infrastructure with smart, high-efficiency distribution assemblies.
In-depth regional review of key growth zones
Rapid industrial development across emerging economies in South Asia drives high-voltage utility investments. Meanwhile, European markets enforce rigorous environmental directives, compelling manufacturers like Rittal GMBH & Co. KG to adopt sustainable, recyclable aluminum architectures and low-emission production methodologies.
Company profiles and strategic positioning of leading enterprises
Industry stalwarts such as Siemens AG, Eaton Corporation plc, and Legrand S.A. maintain dominant market positioning through heavy R&D investment in modular power distribution. Meanwhile, niche players like Mersen S.A. and Rogers Corporation capture specialized segments via advanced laminated busbar technologies.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to fluctuating raw metal commodities, while buyer power is mitigated by the highly customized, safety-critical nature of electrical switchgear. Threat of substitutes is low, yet intense rivalry among established tier-one players compresses margins on standard low-voltage configurations.
SWOT analysis of the Busbar Market ecosystem
Strengths lie in superior electrical conductivity and space-saving efficiency compared to bulky cabling. Weaknesses involve high initial setup costs. Opportunities abound in utility-scale renewable integration, though threats from counterfeit raw materials and regulatory non-compliance loom over unverified regional suppliers.
Value chain analysis from raw materials to end-users
The value stream initiates with raw metal extraction (copper cathode and primary aluminum smelting), transitioning to extrusion and surface treatment by fabricators like Oriental Copper Co. Ltd. System integrators then assemble these components into switchboards before final deployment by utilities and industrial end-users.
Investment insights and high-potential strategic areas
Investors should direct capital toward manufacturers developing lightweight aluminum alternatives and IoT-enabled smart busbars. Companies possessing localized supply chains in high-growth developing regions present the most resilient risk-adjusted return profiles over the forecast horizon.
Conclusion and key takeaways for stakeholders
The Busbar Market represents a high-conviction sector underpinned by a solid 6.04% CAGR through 2033. Success favors firms capable of navigating raw material volatility while delivering energy-efficient, digitally integrated power distribution solutions tailored for modern industrial complexes.
Research methodology and data triangulation practices
Our findings are synthesized through exhaustive bottom-up and top-down triangulations. We combine primary expert interviews with C-level executives, official trade registry statistics from organizations like the International Copper Study Group, and macroeconomic industrial output indices to ensure absolute data integrity.
Scope of the report and coverage parameters
This comprehensive analysis evaluates global busbar deployment across commercial, industrial, and utility domains from 2026 through 2033. The study excludes niche marine and aerospace-specific proprietary wiring harnesses while focusing intensely on heavy industrial and commercial power distribution segments.
Recent developments, partnerships, and strategic corporate moves
Recent market activity highlights aggressive capacity expansions by firms like nVent Electric plc and CHINT Group Co. Ltd. Strategic mergers, acquisitions, and joint ventures focused on EV powertrain integration dominate corporate announcements, signaling an aggressive push toward next-generation electrified transport.